SKU Rationalization: Methods, Costs & Worked Example
SKU rationalization weighs substitution, lost buyers and real savings. Use a worked example to decide which products to keep, change or remove from a range.
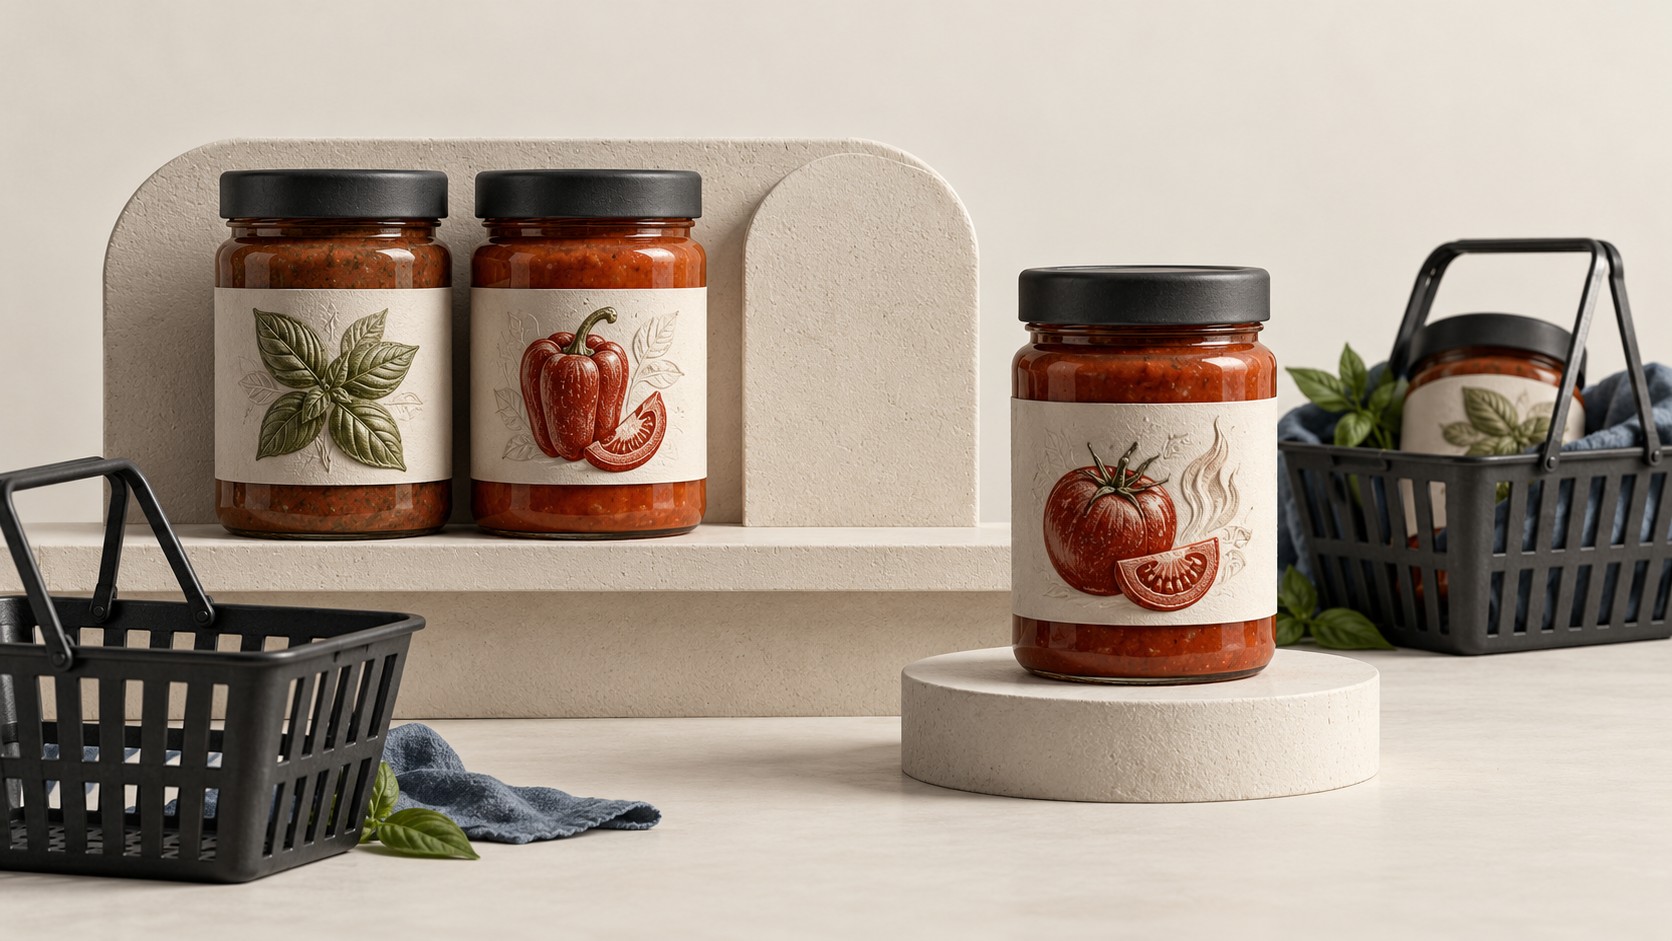
SKU rationalization means deciding which product variants to keep, change or remove. Compare what each contributes, what shoppers would buy without it and which costs would actually disappear. A low sales rank starts the investigation. The removal decision should use the effect on the whole range, including lost purchases and substitution.
The useful research question is: how much of the removed item's contribution would the remaining range recover, and what would the business actually save?
Compare the range with and without the item
A range-selection study asks which set of products covers the most buyer needs. A launch study asks what an additional item would replace. SKU rationalization asks what changes when an existing choice disappears.
That last question needs the current range as its reference. If you show people only the proposed smaller range, you can learn which remaining option they choose. You can't tell whether that choice replaces their previous purchase or whether the smaller range has lost them entirely.
Our TURF analysis guide covers unduplicated consideration across a constrained range. For removal, you also need substitution and the outside option. NIQ's assortment approach explicitly considers demand transfer and the sales risk of delisting. The important change in the research brief is from “Which items look strong?” to “What does each plausible removal do to the whole offer?”
Example: removing a slow-selling sauce
A hypothetical sauce brand sells three 350 g jars. Smoky tomato sells less than basil or roasted pepper. Removing it could simplify production, but some buyers may switch within the brand while others choose competitors, skip the purchase or leave the brand.
All three jars cost $5. The brand is considering removing smoky tomato. The figures below are planning assumptions, not completed-study results.
Current item | Monthly sales and contribution |
|---|---|
Basil, 350 g | 1,000 jars; $2 contribution per jar |
Roasted pepper, 350 g | 600 jars; $2.20 contribution per jar |
Smoky tomato, 350 g | 200 jars; $1.80 contribution per jar |
Here, contribution means sales less the variable costs assigned to each jar. The smoky variant also creates $180 a month of production and handling cost that finance says would disappear if it were removed. That cost isn't included in the $1.80 figure; otherwise the saving would be counted twice.
The 200 smoky-tomato purchases represent purchase occasions, each involving one jar. They aren't assumed to be 200 different people. A household buying the variant every week could account for several occasions, and losing that household might affect other products in its basket.
Check what the item uniquely offers: taste, pack, price or use occasion. Do its buyers also purchase other items? Did sales fall because demand weakened or stock was missing? Frequent stockouts reduce the chances an item has to sell.
Where the displaced purchases go
Consider two possible allocations of those 200 occasions after removal:
Destination | Stronger retention / weaker retention |
|---|---|
Basil | 80 jars / 40 jars |
Roasted pepper | 60 jars / 30 jars |
Competitor, another category or no purchase | 60 occasions / 130 occasions |
Within-brand retention | 140 of 200, or 70% / 70 of 200, or 35% |
The outside choices remain in the base. A test that forces every shopper to select basil or pepper would manufacture complete retention.
With stronger retention, the brand recovers $292 in contribution: 80 × $2 plus 60 × $2.20. Removing smoky tomato loses its $360 contribution, while avoiding $180 in cost. The monthly change is therefore:
$292 recovered − $360 removed + $180 saved = $112 more contribution.
With weaker retention, recovered contribution is $146. The same calculation gives $146 − $360 + $180 = $34 less contribution.
The original sales rank has not changed. Different assumed substitutions change the decision. Under these costs, the brand needs at least $180 of recovered contribution to break even. Focus research on whether that recovery is plausible and how uncertain it is.
A comparison buyers can actually make
Use a defined shopping situation with the current products, realistic prices and feasible alternatives. Compare the existing range with a version in which only the proposed item is removed. Keep the relevant display and availability conditions consistent, and allow a competing product, postponement or no purchase.
Give comparable groups their first encounter with one arrangement when you need an independent range comparison. A later direct comparison can help explain why someone objects to a removal, but it isn't the same as an ordinary first shopping encounter. Our shopper research guide works through this distinction with a constrained shelf.
Check current buyers of the item separately. General category buyers may make a niche item look unnecessary because most never bought it. Show valid response counts for both groups so the team can see whose choices change.
The report should connect the old choice with its replacement. If records can't support that link, label the source of switching unknown. Don't infer it by subtracting two unrelated sets of preferences.
Sapien can compare defined range scenarios with a simulated audience and explore the reasons behind its choices. Observed sales transfer still needs transaction or pilot evidence.
The decision sheet finance and category teams can share
Keep the calculation close to its evidence:
Decision input | What belongs beside it |
|---|---|
Removed contribution | Current units, period, price, variable-cost definition and availability |
Recovered contribution | Destination item, transferred units, contribution per unit and evidence source |
Avoided cost | The specific cash or operating cost that actually disappears, with its owner |
Other effects | Basket changes, service commitments, shelf constraints and transition costs |
Uncertainty | Alternative transfer and saving assumptions that could reverse the decision |
Freed production capacity is not necessarily a cash saving. Fixed overhead may remain, and a replacement may need setup or stock. Ask finance which costs really disappear instead of treating an allocated share of overhead as a saving.
The result also needs the retailer's operational view. A smaller range may improve availability of retained products, but that improvement has to occur in the proposed arrangement. Store capacity, replenishment and supplier terms belong in the feasible comparison.
A reversible removal before a permanent one
Where practical, trial the smaller range before full withdrawal. Record stock availability, competitors, promotions, units, sales value and contribution over comparable periods. Use a suitable comparison design. A before-and-after difference alone cannot show what the removal caused.
Watch the buyers whose needs the item uniquely served. Total brand units can recover while a smaller group leaves; that can be acceptable or unacceptable depending on the range's purpose and the economics. State that trade-off rather than hiding it inside an average.
Remove an item when its absence improves the business after substitution, lost purchases, real savings and operational consequences have all been counted. A low sales rank alone doesn't settle that decision.